
Understanding How Your Role Changes and Why It Matters
At a high level, feeder funds are not difficult to understand. Capital is raised from a group of investors, pooled into a single entity, and that entity invests into a larger syndication. From a structural standpoint, it’s a clean way to organize capital and participate in deals without being part of the general partner group. That’s what makes the strategy appealing.
Table of Contents
- Understanding How Your Role Changes and Why It Matters
- The Structure Works But the Role Has Changed
- Where the Investment Adviser Act Comes In
- Why This Is Often Missed
- How This Fits with the Investment Company Act
- Multistate Regulation Recognition, Not Avoidance
- Bringing It Back to the Bigger Picture
Where things start to become more nuanced is not in the concept itself, but in the regulations that apply when using a feeder fund (aka fund of funds) structure.
The Structure Works But the Role Has Changed
In a traditional GP model, capital raising is typically one part of a broader set of responsibilities. You’re involved in the deal itself. You have a defined role within the management structure. The capital raising activity is tied to that role and the overall execution of the investment.
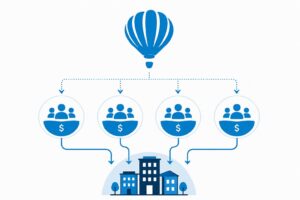
A feeder fund creates a different dynamic. Instead of participating as part of the operating group, you are organizing capital through a separate entity. Investors are coming into that structure based on your relationship with them and your presentation of the opportunity.
That shift may seem subtle at first. In practice, it’s a meaningful change in how your involvement is viewed.
One of the most common ways people think about feeder funds is as an extension of traditional capital raising. People view it as a more efficient way to bring investors into a deal. The mechanics look familiar, and the end result is the same. Capital goes to acquire and improve the asset.
But the activities behind the scenes are different. When you’re building a feeder fund, you’re not just introducing investors to a sponsor. You’re negotiating the investment with the syndicator and structuring the investors participation through the feeder fund. You’re organizing how capital is pooled.
Investors are not simply evaluating the deal or asset syndicator themselves. They are also relying on how you’ve structured the feeder fund for access to it.
That distinction is where additional regulatory considerations begin to enter the picture.
Where the Investment Adviser Act Comes In
The Investment Adviser Act is not always the first thing people think about when they start using feeder funds. Most of the focus tends to be on securities exemptions, particularly Regulation D, and whether the offering itself is structured properly. That’s an important piece of the analysis, but it’s not the only one.
The Investment Adviser Act looks at a different question. It focuses on whether someone is in the business of providing advice or making decisions about investments for others, particularly when that activity is tied to compensation.
When you are organizing a feeder fund, the way your role is raising capital while advising or advocating for a particular investment. You’re presenting the investment in a favorable light and “pitching” a indirect securities investment.
If investors are relying on you to identify the opportunity, structure and negotiate their participation, and determine how the feeder fund contributes funds, those activities resemble investment advisory functions, depending on how they are carried out.
That does not automatically mean the Investment Adviser Act applies in every case. There may be exemptions at the federal and state levels. It does mean the analysis needs to be considered.
Why This Is Often Missed
In practice, most people don’t set out to create an investment advisory relationship. They are focused on participating in a deal, working with investors they know, and using a structure that allows them to do that efficiently. The feeder fund becomes a practical solution to a structural problem.
Because the strategy works operationally, it’s easy to assume the legal framework follows the same path. That’s where issues tend to develop. State and federal regulations become ignored.
How This Fits with the Investment Company Act
In many feeder fund structures tied to real estate or business acquisition syndications, the underlying investment vehicle is relying on exemptions under the Investment Company Act, primarily the 3(c)(1) exemption.
The feeder fund invests capital into another security of the syndication PPM. Since it’s not a direct real estate investment, the real estate exemption does not apply. The Investment Company Act’s real estate exemption normally applies to a GP managed real estate syndication because it’s directly acquiring the property rather than investing through a different fund.
That framework addresses how the fund itself is treated from an investment company standpoint. It does not answer the question of how the person organizing the feeder fund is viewed in relation to the investors. Those are separate considerations.
Understanding that distinction helps clarify why both analyses matter, even though they are often discussed together.
The presence of Investment Adviser Act considerations does not mean feeder funds should be summarily avoided.
Multistate Regulation Recognition, Not Avoidance
It means regulatory analysis needs to be aligned with the role you are actually playing. In a feeder fund, that is generally as an investment advisor investing into an investment company. The goal of the feeder fund promoter is to look at appropriate exemptions.
For state law considerations, feeder funds need to consider the laws of every state that an investor resides as well as where the feeder funds management is located. This creates a patchwork of laws all of which need to be considered to maintain legality.
If not registered as an investment advisor, then the feeder fund manager must look for exemptions from registration. In some states, it requires only working with qualified (super high net worth) clients. In other states, it’s no more than 5 investors or 5 funds within the state. More often states are requiring the same filings as what are required by exempt reporting advisors. This process can require a 50 state evaluation to remain legal.
There are ways to approach these structures that take those considerations into account. In many cases, it comes down to how responsibilities are defined, how decisions are made, and how the relationship with investors is framed.
The goal is not to eliminate participation. The goal is to ensure the exemptions from regulations are properly maintained.
Bringing It Back to the Bigger Picture. Feeder funds are becoming more common because they solve a real problem in the market. They allow capital to be organized efficiently. They allow sponsors to keep their GP structures focused. They give capital raisers a way to stay active in deals without taking on operational responsibilities. All of that still holds true.
At the same time, the shift away from the GP model changes how your role fits as a feeder fund manager investing into a securities syndication and not directly into an asset. Once you begin organizing capital through your own entity, the analysis moves beyond the deal itself and into how that role is defined.
The mechanics of feeder funds are relatively straightforward. The implications of how they are structured are where the differences begin to show. Understanding that distinction early makes it much easier to build a structure that works not just for a single deal, but over time as your capital raising strategy evolves.
If you’re using feeder funds or considering them as part of your approach, it’s worth stepping back and looking at whether your planned feeder fund meets all regulatory exemption requirements. If you’d like to walk through that in more detail, you can schedule a consultation to map out the right approach based on your specific situation.